
If your mortgage payments have become hard to keep up with, you likely have more choices than it feels like right now. Knowing what your home is worth, how much equity you may have, and what a sale on the open market could look like gives you solid information to bring to your lender and advisors.
Request a Confidential Home Sale & Equity Assessment Speak With Kyle: 613-355-0181No obligation · Private & confidential · Speak directly with an Ottawa Broker
Mortgage arrears are missed mortgage payments that are now past due. In Ontario, if missed payments continue, the mortgage goes into default and the lender can take enforcement steps, most often a power of sale under the Mortgages Act. Until the lender actually sells, the owner can often still sell the home on the open market, or bring the mortgage back into good standing. How much room you have depends on where you are in the process, so the most useful early steps are to talk to your lender, get legal advice if you have received formal notices, and find out what your home is realistically worth.
Falling behind on your mortgage does not automatically mean you have to sell. Lenders deal with payment problems regularly, and many would rather agree on a plan than start enforcement. Depending on your lender and your situation, options may include a temporary payment deferral, a longer amortization, a revised payment arrangement, refinancing, or bringing the arrears up to date with help from family or other savings.
If you are having trouble, contact your lender or a licensed mortgage professional as early as you can. The Financial Consumer Agency of Canada expects federally regulated banks to work with customers who are at risk of falling behind; its guide to mortgage relief options is a good place to start.
Whatever you decide, every one of those conversations goes better when you know five numbers:
A realistic sale range based on recent comparable sales, not an online estimate.
Every mortgage, line of credit and lien registered on title, plus arrears and fees.
Commission, legal fees, mortgage penalties and discharge fees, and adjustments.
What could be left for you after everything is paid out at closing.
If the sale might not cover all the debt, you need to know early.
A real estate assessment is one part of your decision, not the whole plan. Your lender, a mortgage broker, a real estate lawyer and, where debts go beyond the house, a Licensed Insolvency Trustee each cover a different piece. My role is the property: what it is worth, what a sale would cost, and what a sale could realistically look like.
If you miss mortgage payments and do not catch up, the mortgage goes into default and your lender can begin enforcement, which in Ontario usually means a power of sale. The process has minimum waiting periods set by law, but costs build up at every stage.
Every mortgage and every lender is different, but the general sequence looks like this:
The lender will usually contact you. Interest keeps accruing, and many mortgages allow NSF or late fees. The missed amounts are your arrears. Missed payments may also be reported to credit bureaus.
Your mortgage terms define what counts as default. A missed payment normally does, and so can unpaid property taxes, lapsed home insurance or unpaid condominium fees.
If default continues, the lender’s lawyer may send a demand letter and then a formal Notice of Sale under Mortgage. Under Ontario’s Mortgages Act, a Notice of Sale generally cannot be given until the default has continued for at least 15 days, and the notice must allow at least 35 days before the lender can sell. Your mortgage terms may provide longer periods.
After the notice period, the lender may take possession and sell the property through power of sale, or ask the court for foreclosure. It may also sue for the amount owing. Other lenders with charges on title may take their own steps.
Legal fees, enforcement costs and ongoing interest are generally added to the balance. The longer the process runs, the less equity tends to remain.
General information only. This page is not legal, mortgage, financial, insolvency or tax advice. Individual circumstances differ. If you are facing mortgage default or have received legal documents, get advice from your lender and an Ontario real estate lawyer or other appropriate licensed professional.
In a power of sale, the lender sells your home but you remain the owner until that sale closes, and any surplus is paid out. In a foreclosure, a court transfers ownership to the lender. Most Ontario lenders use power of sale because it is generally faster and less costly.
| Power of Sale | Foreclosure | |
|---|---|---|
| Who sells and controls the property | The lender, using the power of sale in the mortgage and the Mortgages Act. A court order is not usually required. The lender chooses the listing brokerage, price and offers. | A court process. If the lender obtains a final order, it becomes the owner and can later deal with the property as its own. |
| What happens to the sale proceeds | Generally applied to the lender’s sale and enforcement costs and the mortgage debt, then to later registered charges and claims in order of priority. | The lender owns the property, so proceeds of any later sale are generally the lender’s. |
| Surplus proceeds | Any money left after the mortgage and other registered claims are paid is generally paid to the owner. | Generally no surplus is paid to the former owner. |
| Shortfall | If the sale does not cover what is owed, the lender can generally sue the borrower and any guarantors for the balance. | A final foreclosure generally ends the lender’s right to pursue a shortfall, unless the foreclosure is reopened. |
| Ownership | The owner stays on title until the lender’s sale closes. | Title transfers to the lender through the court process. |
| Legal advice | Strongly recommended as soon as you receive a Notice of Sale. There are firm deadlines. | Strongly recommended as soon as you are served with court documents. There are court deadlines to respond. |
Simplified summary for general information. The exact rights and outcomes depend on your mortgage terms, the steps taken and the court. The Mortgages Act is on Ontario’s e-Laws site. Looking at this from a buyer’s side? See power of sale and foreclosure homes in Ottawa.
Often, yes. As the registered owner, you can generally list and sell your home while you are behind on payments, and in many cases after a Notice of Sale has been served, as long as your sale closes before the lender sells and pays out what is owed.
What is possible depends on your circumstances and how far enforcement has gone. The closer you are to the lender’s own sale, the fewer choices you tend to have. Once a lender has accepted a firm offer from its own buyer, your options may be very limited.
At closing, your lawyer pays the mortgage from the sale proceeds, including arrears, interest, any prepayment penalty and the lender’s enforcement costs, and the mortgage is discharged from title.
Listing your home does not pause enforcement. Unless your lender agrees otherwise, it can continue with the power of sale process while your home is on the market, and a buyer’s closing date needs to fit that timeline.
If enforcement has started, or you have received a Notice of Sale, statement of claim or other legal documents, speak with an Ontario real estate lawyer before you list, and keep your lender informed.
A private estimate of your home’s value, selling costs and likely equity, so you can compare it with your other options.
If the mortgage and other registered debts are more than the net amount a sale would bring in, you have negative equity. You can still sell, but the sale usually needs cooperation from the lenders involved, and any unpaid balance may still be owed.
A mortgage is discharged from title when it is paid. If the net proceeds cannot pay every registered debt in full, you need the lender’s cooperation or consent to discharge its security for less, or you need to cover the gap from other funds at closing. This is sometimes called a short sale. A lender is not required to agree, and agreeing to discharge the mortgage does not necessarily mean it forgives the remaining balance, unless it agrees to that in writing.
The sale is expected to pay all debts and costs with money left over. This is an ordinary sale, and timing is the main concern.
The sale should cover the debt, but only just. Pricing, presentation and selling costs make a real difference to what, if anything, is left.
The sale may not cover everything owed. Lender consent and legal advice are needed before you commit to a sale.
A sale with a shortfall is more complicated than an ordinary sale. Involve an Ontario real estate lawyer and speak with your lender before you list. If your debts are larger than the house, a Licensed Insolvency Trustee can explain your options. I am a real estate Broker, not a lawyer or debt negotiator: my role is pricing, marketing and selling the home, and giving you and your advisors accurate numbers to work from.
Without a realistic value, it is hard to judge any option, including staying put. The Confidential Home Sale & Equity Assessment is a private, written estimate that puts the key numbers in one place.
| Estimated sale price | $650,000 |
| Approximate mortgage balance | − $590,000 |
| Other secured debt | − $10,000 |
| Estimated selling and closing costs | − $25,000 |
| Estimated remaining equity | $25,000 |
If the same home sold for $620,000 with about $24,000 in costs, the result would be roughly a $4,000 shortfall instead. A small change in price can change the whole picture.
This example is illustrative only and is not based on any real property. Your figures will differ.
The assessment is an informational estimate from a real estate Broker. It is not an appraisal, and it does not replace legal, mortgage, financial or insolvency advice. The exact amount needed to pay off your mortgage, including any penalty, comes from your lender’s payout statement.
When you have plenty of equity, a few thousand dollars in costs is easy to absorb. When equity is thin, every cost comes directly out of what you walk away with, or adds to a shortfall.
Costs to plan for usually include real estate commission, legal fees, any mortgage prepayment penalty and discharge fees, arrears and charges the lender has added, and closing adjustments for property taxes or condo fees. The Financial Consumer Agency of Canada notes that federally regulated lenders may waive prepayment penalties in some hardship situations, so it is worth asking your lender directly.
Commission is negotiable and is set out in writing in the listing agreement. We will go through it, line by line, in your estimate before you sign anything.
Four steps, at your pace. You can stop after any of them.
A private call about your home, your timeline and what you want to find out. Share only what you are comfortable sharing.
I review recent comparable sales and prepare your estimate of value, costs and likely equity or shortfall.
We look at pricing, preparation and timing against your lender’s timeline and any advice you have received.
If selling makes sense, we prepare the home and bring it to market. If it doesn’t, you keep the information.
Legal, mortgage and insolvency questions should be handled by qualified professionals. Where it helps, I can work alongside your lawyer and lender so everyone is using the same numbers.
These are the kinds of things Ottawa homeowners say when they first get in touch. In every case, the starting point is the same: know what the home is worth and get the right professional advice.
My mortgage renewal increased my payment substantially.
Knowing your equity helps you compare renewing, refinancing, renting part of the home or selling.
I’ve missed several mortgage payments.
Call your lender first. A current value tells you whether a sale would clear the arrears and the mortgage.
My private mortgage is coming due.
If renewal or refinancing isn’t available, the payout amount and your sale range decide how much time you need.
My lender has sent me a demand letter.
Speak with a real estate lawyer now. A valuation shows what an owner-controlled sale could realistically produce.
My spouse and I have separated and we can’t keep the house.
Both owners usually need to agree on a sale. See selling a home during separation or divorce.
I’ve lost my job and I’m falling behind.
Ask your lender about relief first. Knowing your numbers helps you decide how long you can realistically wait.
My home may not be worth enough to cover all the mortgages.
An accurate value is the first step. From there, your lawyer and lenders can discuss what a sale would require.
I received documents mentioning power of sale.
Take them to an Ontario real estate lawyer promptly. Deadlines apply, and your options depend on the timing.
Because a fast offer is easier to judge when you know what the same home would likely sell for on the open market, and what you would actually take home from each option.
Homeowners under financial pressure are often contacted by investors or companies offering to buy quickly, sometimes for cash and without showings. For some people that is the right fit, especially when speed and certainty matter more than price, or the home needs major work. The point is to make that choice with both options in front of you.
Have a lawyer review any agreement before you sign, particularly one that includes a lease-back, an option to buy the home back later, or a transfer of title before closing.
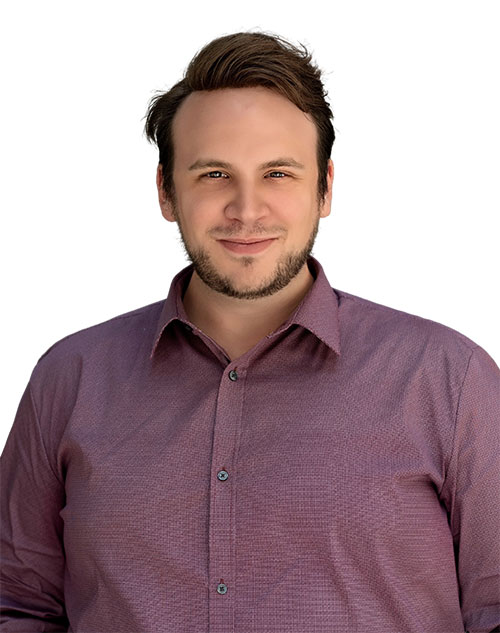
I have spent 12 years selling real estate in Ottawa. When a homeowner is under financial pressure, the job is the same as any sale, done with more care: price it accurately, present it well, reach as many buyers as possible, and keep a close eye on what the seller will actually net.
I work with homeowners throughout Ottawa, from Kanata, Stittsville and Barrhaven to Orléans, Nepean, Riverside South and Manotick, and in nearby communities including Carleton Place, Almonte, Arnprior, Kemptville, Rockland and Embrun.
Your lender will usually contact you, interest continues to build, and you may be charged NSF or late fees. Under most mortgage terms, a missed payment puts the mortgage in default. One missed payment rarely leads straight to a sale, but if the default continues the lender can begin enforcement, usually a power of sale. Missed payments may also be reported to credit bureaus. Contacting your lender early usually gives you the most options.
Generally, yes. You are still the owner. When the sale closes, your lawyer pays the mortgage from the proceeds, including the arrears, interest, any prepayment penalty and the lender’s costs, and the mortgage is discharged. If the proceeds will not cover every registered debt, you will need your lender’s cooperation before the sale can close.
In many cases, yes, as long as your sale closes before the lender’s sale and pays out what is owed. Listing the home does not stop enforcement on its own; the lender can generally continue the process while your home is on the market. Your options narrow as the lender’s own sale gets closer, so if you have received a Notice of Sale, speak with an Ontario real estate lawyer before you list.
Under Ontario’s Mortgages Act, a lender generally cannot give a Notice of Sale until the default has continued for at least 15 days, and the notice must allow at least 35 days before the property can be sold. Some mortgages set longer periods. In practice the full process often takes several months, but it varies with the lender and the circumstances. These are general statutory minimums, not legal advice. Ask an Ontario real estate lawyer how the timelines apply to your mortgage.
The sale proceeds are generally used to pay the lender’s sale and enforcement costs and the mortgage debt, then any later registered mortgages or claims in order of priority. Anything left over is generally paid to the owner. Because legal fees, interest and carrying costs are added along the way, owners usually keep less equity in a power of sale than they would in a well-managed sale of their own.
The difference, often called a shortfall or deficiency, is generally still owed. The lender may pursue you, and any guarantors, for the balance. Depending on your situation, you may be able to negotiate repayment or a settlement. Speak with a lawyer, and if your debts go beyond the home, a Licensed Insolvency Trustee.
A short sale is a sale where the net proceeds are less than the debts registered against the property, so the lender has to agree to accept less than it is owed before it will discharge its mortgage. It is not a separate legal process in Ontario. A lender agreeing to discharge its mortgage does not necessarily mean it forgives the rest of the debt, so get the terms in writing and have a lawyer review them.
It is possible, but it takes planning. You will generally need your lender, and any other secured creditors, to consent to discharging their security for less than what is owed, or you will need to cover the gap from other funds at closing. Talk to your lender and an Ontario real estate lawyer before you list.
Not usually for an ordinary sale that pays every registered debt in full at closing. You simply pay out the mortgage, including any penalty. You will need the lender’s agreement if the proceeds will not cover what is owed. Check your mortgage terms, and keep your lender informed if you are in arrears or enforcement has started.
Yes. Private mortgages often have short terms, higher interest rates and fees, and the payout may include charges set out in your commitment or mortgage terms, so ask for a payout statement early. If a private mortgage is coming due and you cannot renew or refinance, selling is one option to compare. The Financial Services Regulatory Authority of Ontario has a plain-language guide to alternate and private mortgages.
A home equity line of credit is secured by a charge registered on your title, so it normally has to be paid off and the charge discharged when you sell. If your HELOC is part of a combined or readvanceable mortgage, every part secured by that charge usually has to be paid. Ask your lender for a payout statement that covers each one.
It depends on whether the problem is temporary or long term, how much equity you have, and what your lender can offer. Start by asking your lender about relief options, and get financial advice if you need it. Then compare those options with a realistic estimate of what a sale would leave you with. Selling may make sense if the payment is not sustainable and you have equity to protect, but the decision is yours.
It can be a reasonable choice if speed and certainty matter more than price, or the home needs significant work. Before accepting, compare the offer’s net proceeds with a realistic open-market estimate, and have a lawyer review the agreement, especially any lease-back or buy-back terms. Knowing both numbers lets you choose with confidence.
It depends on the price range, property type, condition, location and time of year. Preparing a home for market often takes one to two weeks. Time to find a buyer ranges from days to months, and closing usually happens 30 to 90 days after an agreement becomes firm, though a shorter closing is possible if the buyer agrees. Plan your timing around your lender’s timeline and your lawyer’s advice.
Contact an Ontario real estate lawyer promptly, because the notice sets deadlines. The Law Society Referral Service can help you find one. Keep talking with your lender or its lawyer, and consider a mortgage broker if refinancing may be possible. If your debts go beyond the home, speak with a Licensed Insolvency Trustee. A real estate Broker can tell you what your home is likely worth and what an owner-controlled sale could look like.
The information on this page is general information only and is not legal, mortgage, financial, insolvency or tax advice. Individual circumstances differ. Homeowners facing mortgage default or legal enforcement should get advice from their lender and appropriate licensed professionals.
If mortgage payments are becoming difficult, understanding your home’s current market value and estimated equity can help you evaluate your options.
Request My Confidential Home Sale & Equity Assessment Call Kyle: 613-355-0181Only three fields are required. Share financial details only if you want them included in your estimate. Prefer to talk it through? Call or text Kyle at 613-355-0181.
Your information will be kept private and used only to respond to your request.
Kyle Dawson, Broker, HouseSigma Inc., Brokerage. Not intended to solicit sellers currently under contract with another brokerage.